

Strongest take-up growth is taking place outside the major metropolitan areas
Logistics market ramps up leasing take-up by 1 million m²
Frankfurt, 30 October 2026
The German market for warehouse and logistics space grew significantly in the first three quarters of 2026. Take-up totals around 5.36 million m², exceeding the previous year's figure of 4.36 million m² by around one million square metres or 23 percent. The comparable five-year and ten-year averages were also exceeded, albeit only slightly, by two and four percent respectively. At 524 contracts, the number of deals was on a par with the previous year. The increase in take-up is mainly due to the rise in deals of 10,000 m² and more: 179 contracts have been registered in this segment so far in 2026, 33 more than in the same period last year.
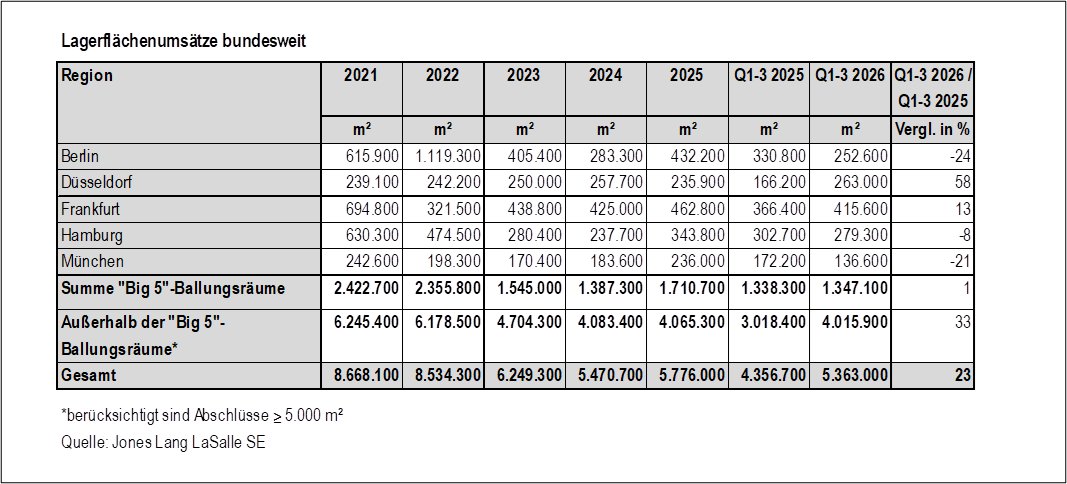
Warehouse take-up across Germany (deals ≥ 5,000 m² included). Copyright: JLL.
While take-up from leasing rose by 43 percent compared with the previous year, owner-occupier take-up fell by 26 percent. At around 907,600 m², owner-occupiers contributed only 17 percent to the result. “Experience shows that the fourth quarter is often the strongest. If that is confirmed, we could break the seven million m² take-up mark this year,” says Sebastian Bögel, Head of Industrial & Logistics Agency JLL Germany, looking ahead to the coming months.
Take-up in the five metropolitan areas stable overall, with regional differences
Take-up in the five major conurbations of Berlin, Düsseldorf, Frankfurt, Hamburg and Munich reached around 1.35 million m² in the first three quarters of 2026, matching the previous year's level. However, the regions fell short of the five-year comparative figure by eight percent. Once again, the region with the highest take-up was Frankfurt with 415,600 m², an increase of twelve percent year on year. Hamburg (279,300 m², minus eight percent), Düsseldorf (263,000 m², plus 58 percent) and Berlin (252,600 m², minus 24 percent) follow at a considerable distance. At 136,600 m² and a decline of 21 percent, Munich recorded the lowest take-up among the five metropolitan areas.
Companies from the transport, traffic and warehousing segment proved to be the most active user group, with take-up of 605,600 m² – 45 percent of total take-up and an increase of around 43 percent on the previous year. One of the largest deals in this sector was the lease of around 40,000 m² by the Chinese logistics service provider JD Logistics in Ludwigsfelde near Berlin.
Industrial companies, on the other hand, recorded a decline of nine percent to 341,500 m²; the largest deal here was the lease of around 32,000 m² by Siemens in Offenbach (Frankfurt region). Despite the largest deal so far – the lease of more than 50,000 m² by a well-known online retailer in Hamburg-Allermöhe – retail companies recorded a decline of 34 percent to 227,800 m².
Scarce supply drives prime rents up
Significantly less supply is still coming onto the market than in the previous year. From January to September, at around 219,000 m², only half as much warehouse space was completed in the five metropolitan areas as in the same period last year. Compared with the five-year average, the decline is as much as 57 percent. At the time of completion, only around 70,000 m² (32 percent of the space) was still available, 52 percent had already been let and the remaining space had been allocated to owner-occupiers. “As modern space available at short notice is lacking in many metropolitan areas, the situation remains tight,” says Bögel. Construction activity looks more positive: at around 883,000 m², a good 60 percent more space is currently under construction than a year ago, of which around 55 percent is still unlet. Berlin has the highest construction activity with around 319,000 m², Hamburg the lowest with around 116,000 m².
In the third quarter, prime rents for warehouse space of 5,000 m² and more rose by 4.8 percent to EUR 11.00/m²/month in Berlin and by 2.8 percent to EUR 9.25/m²/month in Düsseldorf. In the other metropolitan areas, rents remained stable. Munich now leads together with Berlin at EUR 11.00/m²/month each. In Hamburg and Frankfurt, EUR 8.50/m²/month is achieved in each case. According to Bögel, further rental increases are to be expected here, too.
Regions outside the metropolitan areas grow significantly faster
At around 4.02 million m², around one third more square metres were taken up outside the five major conurbations in the first nine months of 2026 than in the same period of the previous year (Q1–Q3 2025: 3.02 million m²). The five-year average was exceeded by six percent, the ten-year average by eight percent. Around 20 percent of total take-up was attributable to owner-occupiers.
Companies from the transport, traffic and warehousing sector once again grew significantly year on year (plus around 700,000 m²) and also dominated demand for space in the first nine months of 2026. With a share of around 48 percent, around 1.91 million m² was attributable to this sector. This included seven leases of 50,000 m² or more: contract logistics provider Ceva Logistics leased around 90,000 m² each in Frankfurt (Oder) and in Lich near Giessen. Maersk Logistik signed a contract for around 69,000 m² in Herleshausen in northern Hesse, ID Logistics leased around 67,000 m² in Alsdorf near Aachen and Goodcang Logistics around 65,000 m² in Rieste in Lower Saxony.
Retail companies grew by 25 percent year on year and accounted for 19 percent or 768,600 m² of total take-up. Demand from industrial companies, on the other hand, fell by seven percent to 914,800 m²; compared with the long-term average, the decline is as much as 30 percent.
Chinese companies drive demand in the Ruhr area
With around 487,800 m² and growth of 20 percent over twelve months, the Ruhr area leads the regions outside the five metropolitan areas. Around 43 percent of the take-up generated here is attributable to leases by Chinese companies. The average size of these leases was around 14,200 m². “The Ruhr area continues to benefit particularly strongly from the ongoing demand from Chinese companies,” explains Bögel.
The Hanover/Braunschweig region ranks second with 359,800 m², more than quadrupling the previous year's result. Deals by retail companies dominate here, accounting for 44 percent of total take-up. The lease of around 56,800 m² by Takko Fashion marks the largest deal in the region. The Osnabrück/Münster region takes third place with 259,100 m² and an increase of 185 percent.
Contact: Sebastian Bögel, Head of Industrial & Logistics Agency JLL Germany
Phone: +49 (0) 89 290 088 327
Email: sebastian.boegel@jll.com
About JLL
JLL (NYSE:JLL) is a leading global commercial real estate and investment management company with annual revenue of USD 26.1 billion, operations in over 80 countries and a global workforce of more than 112,000 (as of 30 September 2026). For over 200 years, clients have trusted JLL, a Fortune 500® company, to help them buy, build, occupy, manage and invest in a variety of industries and property types with confidence, including office, industrial, hotel, residential, retail and data centre properties. Driven by our purpose to shape the future of real estate for a better world, we help our clients, people and communities make the right decisions.
Backed by extensive global databases and leading technology expertise, we provide coordinated, holistic real estate services for a broad range of global clients across a wide variety of industries. Through LaSalle Investment Management, we invest on behalf of clients worldwide in both private assets and publicly traded real estate securities.
Latest Warehouse News
Logistics market ramps up leasing take-up by 1 million m²
The German warehouse and logistics market recorded take-up of around 5.36 million m² in the first three quarters of 2026, 23 percent more than a year earlier. According to JLL, the regions outside the five metropolitan areas are growing fastest, and prime rents are rising....
Montea acquires logistics portfolio from WLP and agrees development partnership for Italy
Montea acquires ten logistics properties totalling around 310,000 m² in Italy and Germany from Weerts Logistics Parks (WLP) for EUR 343 million and agrees an exclusive development partnership for Italy until 2030....
Logivest brokers around 20,000 square metres near Bremen for medical care products provider
Logivest brokers around 20,000 square metres of warehouse and office space near Bremen for Unizell Medicare...

GRUBER Logistics expands rail capacities thanks to the acquisition of Hamburg-based freight forwarder Gruber
GRUBER Logistics integrates Hamburg-based Gruber AG and expands rail services via the Brenner...