

REALOGIS: Take-up at Germany's top 8 logistics locations turned positive again in 2025
- 2.78 million m² take-up, up 21% on 2024
- Ruhr area largest submarket with 603,200 m²
- Munich is the most expensive at €13.50/m²
- Leases dominated with 94% market share
- Big box space accounted for 1.62 million m²
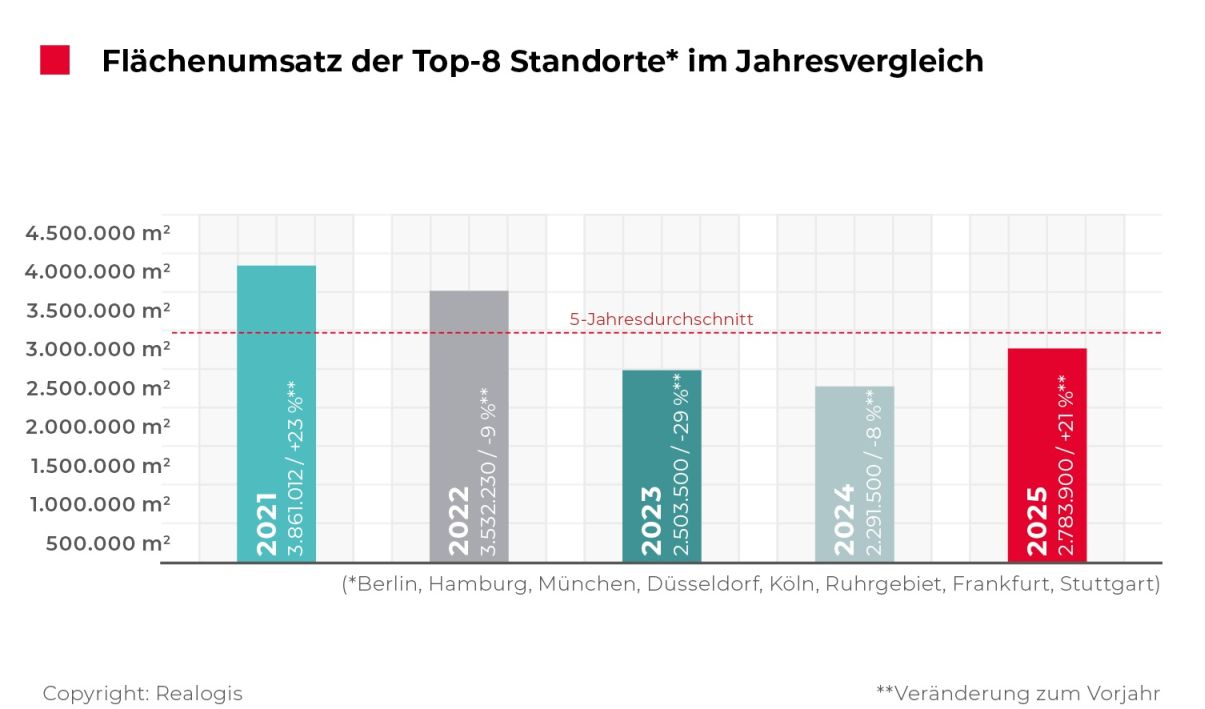
Munich, 24 February 2026 – The REALOGIS Group, Germany's leading consulting firm for industrial and logistics real estate as well as commercial properties, has registered take-up of around 2.78 million m² for the full year 2025 in the top 8 locations defined by the company. Compared to 2024, this corresponded to an increase of 21% and thus the trend reversal after three years of decline. In the previous year, the lowest value since 2014 was recorded. The markets examined include Berlin, Düsseldorf, Cologne, the Ruhr area, Frankfurt, Hamburg, Munich and Stuttgart.
Rental prices: Munich clearly ahead, average rents stabilized
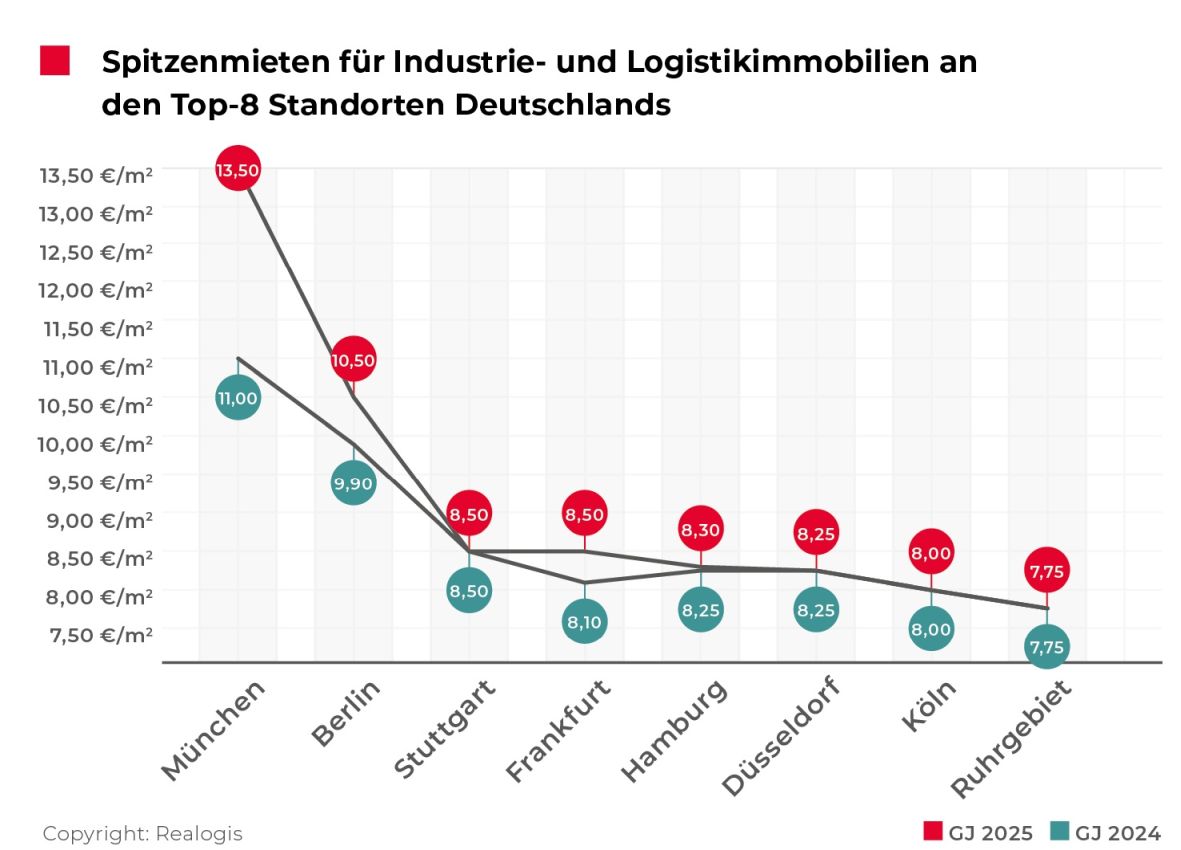
The picture for rents was mixed. Munich took the lead with a prime rent of €13.50/m² and at the same time recorded the strongest increase of 23% or €2.50/m² compared to 2024, followed by Berlin with €10.50/m² (end of 2024: €9.90/m²). Frankfurt and Stuttgart shared third place with €8.50/m² each, with Frankfurt growing and Stuttgart remaining at the previous year's level. The same applied to the rent levels in Düsseldorf and Cologne at €8.25/m² and €8.00/m² respectively. In Hamburg, prime rents rose by 5 ct/m² to €8.30/m² compared to the end of the previous year. The Ruhr area remained the cheapest at €7.75/m².
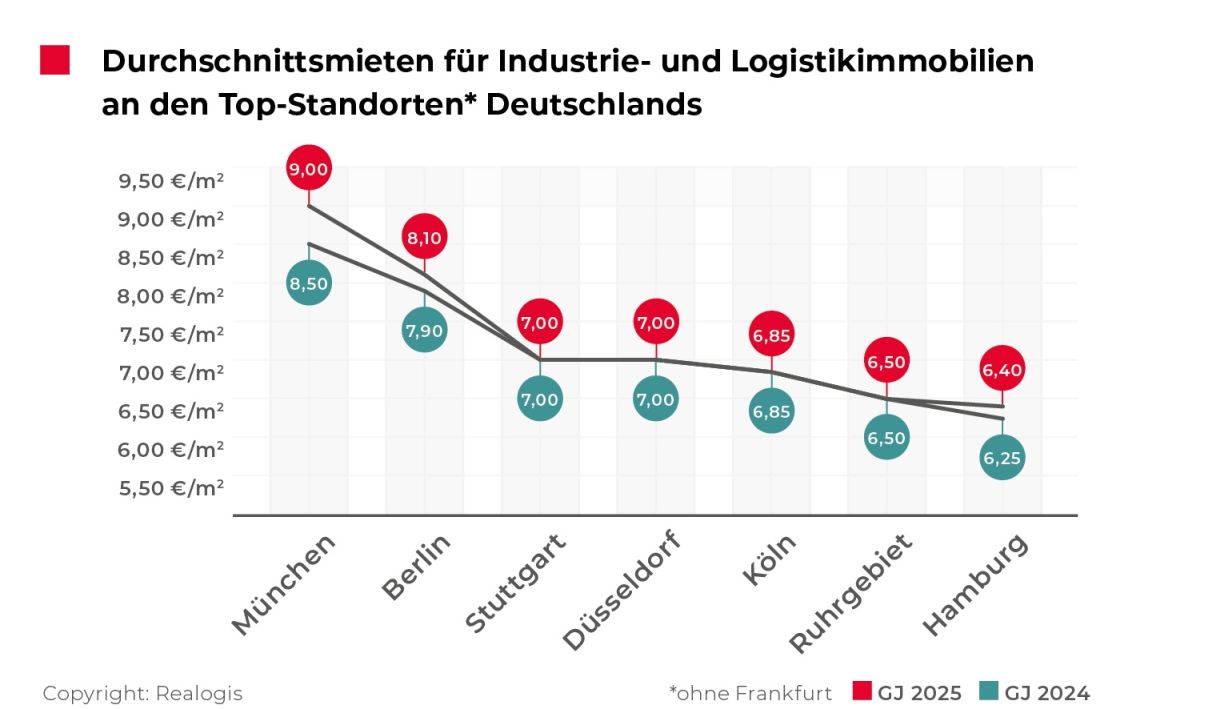
Average rents (excluding Frankfurt) increased by an average of 2% in 2025 compared to the end of 2024. In Munich they were €9.00/m² and in Berlin €8.10/m². Stuttgart and Düsseldorf each reached €7.00/m², Cologne €6.85/m² and the Ruhr area: €6.50/m². In Hamburg, the rent remained the lowest at €6.40/m².
Take-up: Downward trend ended, Ruhr region accounted for the largest share
After three years of declining earnings, take-up in the top 8 locations increased noticeably again in 2025. The strongest percentage increases were recorded in the Ruhr area and Berlin.
The Ruhr region made the largest contribution to the annual result with 603,200 m² and a market share of 22%. It was followed by Frankfurt with 435,200 m², followed by Berlin with 433,000 m².
Compared to the 5-year average, Munich, the Ruhr area and Düsseldorf were the only regions to reach or exceed their reference value. Munich was well above average, as was the Ruhr area, while Düsseldorf reached its average value. Stuttgart lagged behind the most.
Types of contracts: Leases remained decisive, owner-occupiers played a secondary role
In 2025, take-up of space was almost entirely attributable to leases. 94% respectively. 2.61 million m² were attributable to tenants. Owner-occupiers accounted for 6% or 174,400 m². Compared to 2024, the structure thus remained almost unchanged.
Property types: Big box space increased significantly, business parks declined
Big box deals dominated the market and achieved take-up of 1.62 million m² or 58% in 2025. This segment thus recorded the largest growth.
Space in properties outside the big box and business park categories accounted for 758,900 m² or 27%. Business parks brought up the rear with 408,700 m² or 15% and were the only declining category. Overall, the decline in the business parks was more than offset by the growth in big-box and other properties.
User groups: Logistics/freight forwarding clearly ahead, trade in second place
The largest buyers of space in 2025 were companies from logistics/freight forwarding. They accounted for around 1.33 million m² or 48% of take-up, replacing retail as the previous year's leader. In addition, this user group was the only one to exceed the 5-year average.
Retail followed with 757,300 m² or 27% of market take-up. Traditional retail dominated with 492,600 m² or 65% share of take-up. (2024: 460,400 m² / 53%). Leases by e-commerce companies accounted for 264,700 m² or 35% of take-up in this segment (2024: 401,500 m² / 47%).
Industry/production ranked third with 498,400 m² or 18% and increased moderately. Other sectors accounted for 203,000 m² or 7%.
Size classes: Large areas dominated, areas from 5,001 m² gained in importance
Large spaces from 10,001 m² remained the dominant segment, reaching 1.54 million m² or 55% market share. Areas of 5,001 to 10,000 m² followed with 475,000 m² or 17%. Taken together, this means that almost three quarters of take-up was accounted for by space of 5,001 m² or more.
Areas between 3,001 and 5,000 m² and between 1,000 and 3,000 m² declined slightly. Very small areas of less than 1,000 m² were once again the smallest category and recorded the most significant decline.
REALOGIS. The No. 1 in industrial and logistics real estate
The REALOGIS Group is Germany's leading address for advising and brokering industrial and logistics properties as well as commercial properties. As an owner-managed company with locations in Berlin, Düsseldorf, Germany South/North, Frankfurt am Main, Hamburg, Leipzig, Munich and Stuttgart, the company, founded in 2005, has in-depth market knowledge and more than twenty years of experience in the German real estate sector.
Around 70 employees support national and international companies from logistics, industry, trade and e-commerce as well as private and institutional investors. The range of services includes the mediation of tenants for existing and new properties, the support of investors in acquisitions and project developments, advice on the search for or sale of land as well as the development and implementation of holistic real estate strategies, from location analysis to the realisation of assets that are no longer necessary for operation.
Contact Media
Targa Communications
Arne Degener
T +49 151 196 933 90
E ad@targacommunications.de
Latest Warehouse News
Logivest supports JCL Home Delivery Germany again in Cologne expansion
Logivest once again supports JCL Home Delivery Germany in expanding its space in Cologne...
CargoLine expands its Italian expertise: Arco Spedizioni becomes new partner for Milan and Lombardy
CargoLine gains Arco Spedizioni as new partner for Milan and Lombardy...
Logistics take-up continues to rise – particularly high volume in the third quarter
BNP Paribas Real Estate publishes market figures for Q3 2026...
20 years of Gebrüder Weiss in Maria Lanzendorf: an investment with foresight
With the construction of the Maria Lanzendorf branch near Vienna, Gebrüder Weiss set the course for further growth in Austria and Europe. Today, the site is the largest in the entire Group network....